SIP vs Lump Sum Investment: Which Works Better in Different Market Conditions?
Compare SIP and lump sum investing using clear market scenarios and cash-flow assumptions.

Executive summary
SIP vs Lump Sum Investment: Which Works Better in Different Market Conditions?
A SIP invests money gradually; a lump sum puts available money to work immediately.
- Category & Focus
- Personal finance and investing
- Verified Word Count
- 818 words
2026 Reference Edition · Verified Secondary Research
Who This Guide Is For
- Readers evaluating Personal finance and investing.
- Practitioners needing verified benchmarks and calculations.
Important Considerations
- Verify dated prices and regional specifications before committing.
- Review primary source disclosures and product documentation.
A SIP invests money gradually; a lump sum puts available money to work immediately. Neither method guarantees a superior result. The outcome depends on the market path, when the cash becomes available, the return on uninvested cash, and whether the investment matches the goal. Monthly salary investing and staging an existing corpus are different decisions.
Begin with where the money comes from
If you receive ₹10,000 to invest each month, a SIP is simply a scheduled way to invest that income. A fair comparison should not pretend you had ₹1,20,000 available at the beginning of the year. Investing future salary in advance would require borrowing, adding costs and risks.
If you already hold ₹1,20,000, the choice is genuinely between immediate investment and a phased schedule. Staging reduces exposure to the entry price on any single day. It also leaves part of the corpus outside the intended investment while you wait. That opportunity cost belongs in the calculation.
SEBI's investor guidance emphasises goals, risk tolerance and time horizon. Entry method does not repair an unsuitable asset allocation. Money needed soon should not become an equity investment merely because it is invested through a SIP.
Work through three transparent price paths
Take a hypothetical ₹30,000 corpus. Compare buying immediately with investing ₹10,000 at each of three purchase dates. Ignore cash interest, charges and taxes initially, and value everything at the third date. These deliberately simplified paths are illustrations, not historical market evidence.
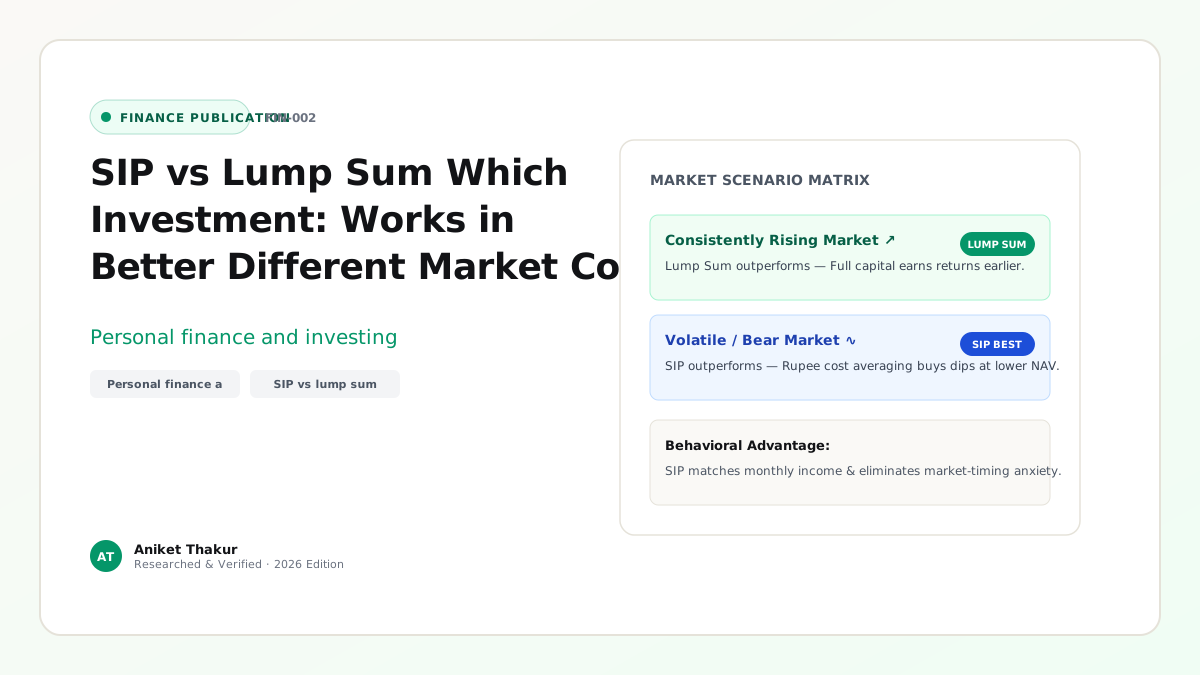
With prices ₹100, ₹110 and ₹120, the lump sum buys 300 units worth ₹36,000. The phased purchases buy about 274.24 units worth ₹32,909. Earlier exposure benefits from the rising prices.
With prices ₹100, ₹90 and ₹80, the lump sum still buys 300 units, now worth ₹24,000. Phasing buys about 336.11 units worth ₹26,889. Later purchases acquire more units at lower prices, but the phased investor has still lost money.
With prices ₹100, ₹80 and ₹100, phasing buys 325 units worth ₹32,500, while the lump sum finishes at ₹30,000. The recovery helps the units bought during the dip. A different recovery date or price could reverse that result.
Build the comparison in Excel
Use columns for date, price, contribution, units purchased and cumulative units. Units equal Contribution/Price. Final value equals total units multiplied by the common final price. For staging an existing corpus, add a cash balance column and the actual after-tax return earned while money waits.
Separate invested-portfolio performance from the performance of the entire original corpus. Counting returns only on deployed money while ignoring idle cash can make a phased strategy look artificially attractive. Use the same final date and include the same fees for both methods.
For genuinely staggered external contributions, calculate investor return using dated cash flows and Excel XIRR. Do not compare a SIP XIRR over one period with a fund's lump-sum CAGR over another. Those figures describe different cash-flow experiences.
Choose a rule you can actually follow
A phased schedule can be useful if investing everything immediately would cause panic selling after a decline. Define the amount, dates and end date in advance. Repeatedly postponing instalments whenever headlines look worrying converts a disciplined schedule into discretionary market timing.
A lump sum offers immediate participation and less ongoing administration. It also exposes the full corpus to an immediate drawdown. Test that possibility in rupees: a hypothetical 25% fall on ₹4 lakh means a ₹1 lakh decline. Consider whether the goal and household cash position can tolerate that.
Keep emergency reserves separate, choose the asset mix first, then choose the implementation method. Review the plan when income or goals change, rather than changing methods merely because the latest month favoured the alternative. No historical average can promise the path your own investment will experience.
Quick questions, clear answers
Does a SIP prevent losses?
No. Buying at several prices changes the average purchase cost but does not create capital protection. A prolonged decline can leave every instalment below its purchase price. The underlying assets, concentration and investment horizon remain central sources of risk.
Should I stop instalments when prices fall?
Revisit affordability and the investment thesis before changing the schedule. A price fall alone does not establish that stopping is wise, but continuing blindly into an unsuitable or changed product is also unhelpful. Maintain necessary household liquidity and assess the actual portfolio exposure.
Is one schedule best for everyone?
No universal number of instalments is established here. Compare a few pre-defined schedules against your cash availability and ability to tolerate losses. Include cash returns and costs. An adviser can help connect the implementation decision with the wider financial plan.
About this guide
Aniket Thakur prepared this educational guide from secondary research checked on 22 October 2026. All numerical illustrations are hypothetical unless stated otherwise. No investment product was tested, and no individual financial circumstances were assessed. Read the cited primary material and relevant product documents before acting.